

SoLo Funds: Lend & Borrow
4.6

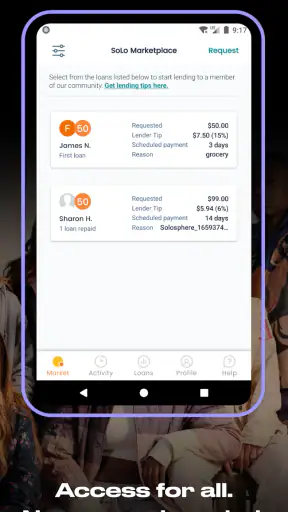
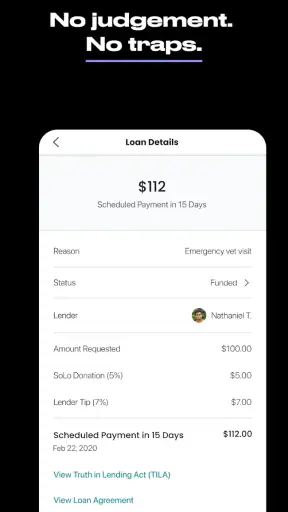
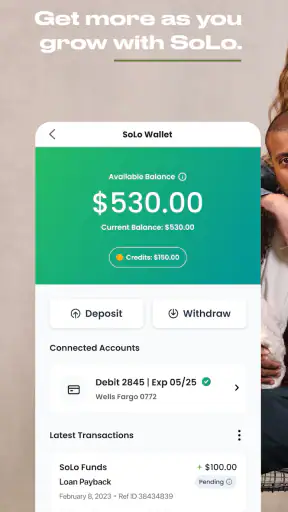
When an unexpected expense appears between paydays, the difficult part is often not finding a financial app but deciding whether its way of working fits your situation. SoLo Funds: Lend & Borrow takes a community-based approach to short-term money: members can request funds on their own terms, while other members can lend and potentially benefit from doing so. I found that this makes the app feel different from a standard budgeting tool or a conventional loan marketplace. It is built around a specific moment of need, not around tracking every part of your financial life.
The app is free, belongs to the finance category, and is developed by Solo Funds. It has a 4.6 average from around 25 thousand ratings, with more than 500 thousand installs. Those figures suggest that the concept has reached a substantial audience, but they do not remove the need to use good judgment. Borrowing through a community platform still requires careful attention to repayment, timing, and the terms shown before accepting anything.
How SoLo Funds feels when speed matters
My first impression is that the experience is designed to get users focused on a request or lending opportunity rather than burying them in unrelated financial tools. That narrow purpose can be useful when I already know what I need to do. Instead of opening a general-purpose banking app and searching through several sections, I can approach the service with a clear question: am I trying to request short-term help, or am I considering lending?
That does not mean every situation becomes instant. The app connects people with one another, so speed depends on the activity around a request and on the steps required to complete the transaction. I would not treat it as a guaranteed emergency cash button. The sensible approach is to begin before the bill becomes urgent, read the complete offer, and keep another plan available if the timing is critical.
For a borrower, the important advantage is control over the request. The service is presented around borrowing on your own terms, which is more personal than simply accepting a fixed product from a traditional lender. Still, flexibility can create responsibility. A request that looks manageable in isolation may become stressful when combined with rent, utilities, subscriptions, or another repayment already due.
For a lender, the attraction is the possibility of helping another person while receiving a benefit in return. That sounds straightforward, but I would approach it as a financial decision rather than as casual spare-change sharing. Money placed into a loan should be money I can afford to have unavailable for a while. The social element may make the experience more approachable, but it should not replace basic risk awareness.
A realistic everyday scenario
Imagine a user whose car repair arrives a few days before payday. The repair is necessary for commuting, but the user does not want to use a credit card with an unfamiliar balance or ask several friends individually. SoLo Funds may offer a more organized way to request short-term assistance. The useful workflow is to calculate the exact gap, request only that amount, inspect the repayment obligation, and decide whether the next paycheck can comfortably cover it.
The key word is “exact.” Asking for a little extra because the app makes it possible can turn a temporary bridge into a larger burden. I would also leave room for ordinary expenses after payday. A repayment plan that consumes nearly the entire next check is not truly comfortable, even if it solves the immediate repair.
What borrowers should examine before accepting
I would treat every screen involving a request, offer, or repayment as something to read slowly. Look for the total amount involved, the expected timing, and any conditions presented in the app. Do not rely on memory from a previous transaction, because your personal circumstances may be different and the details of a new request may not match the old one.
A practical habit is to write down three numbers before proceeding: the amount needed, the amount expected to be repaid, and the date on which repayment must fit into the household budget. This simple check is more valuable than trying to make the app feel faster. It also exposes a common mistake: using a short-term service to cover a recurring shortage. If the same gap appears every month, a longer-term budgeting or income solution is likely more appropriate.
Another useful tip is to use the app for a defined purpose rather than browsing while anxious. Stress encourages optimistic assumptions. If I open the service with a prepared figure and a firm repayment limit, I am less likely to accept an arrangement merely because it appears at a difficult moment.
What happens during heavier use
Heavy use in this app is less about demanding graphics or large media files and more about repeated financial decisions. A borrower may review a request, revisit the details, compare the timing with upcoming bills, and return later to check progress. A lender may examine several opportunities and decide how much money to allocate. In both cases, the mental workload is more important than the phone’s raw power.
That is why I value a focused interface here. Finance apps become tiring when every action requires excessive navigation, especially when the user is already worried about money. SoLo Funds works best when I keep each session purposeful: review the current situation, confirm the terms, and close the app once I have made a considered decision.
I would avoid treating the lending side like a rapid-fire marketplace. Moving quickly from one opportunity to another can make individual decisions feel insignificant, even though each one affects real funds. A better routine is to set a personal limit, review one opportunity at a time, and keep a record of money committed through the service. That record is especially useful if I lend more than once, because a collection of small amounts can become a meaningful total.
Borrowers also need to think beyond the moment when money arrives. The app may help organize the request, but it cannot make the underlying expense disappear. I would use the waiting period to prepare for repayment: pause optional purchases, check the next pay cycle, and identify what happens if income arrives late. This is an important trade-off. The convenience of a dedicated borrowing platform can make a short-term solution feel cleaner than it really is.
Resource demands and day-to-day handling
SoLo Funds is a finance app rather than a graphics-heavy game, so my expectations for device demand are modest. The more relevant question is whether the app remains comfortable during ordinary financial tasks: opening an account area, reviewing a transaction, checking a request, or returning to a previous decision. I found the concept better suited to short, intentional sessions than to constant background use.
I would not keep it open simply because I am waiting for a response. Closing the app between checks is a sensible habit for both attention and battery, and it prevents me from repeatedly refreshing out of impatience. The service is most useful when I decide when to check rather than allowing the possibility of a new update to dominate the day.
On an older phone, the experience may feel less comfortable if the operating system is close to its minimum supported level. The listed minimum is Android 8.0, so users on an older device should make sure the phone is updated as far as it can reasonably go and has enough free storage for normal app operation. I would also avoid making a time-sensitive financial decision on a device that is already struggling with general stability.
Reliability, recovery, and the limits of convenience
Reliability matters more in a money app than in an entertainment app. If a game takes longer to load, I can try again later. If a financial screen is unclear or a session is interrupted while I am reviewing an obligation, I need confidence that I can return without guessing what happened. My preferred approach is to pause after any interruption, reopen the relevant area, and verify the current status instead of assuming that a previous tap completed successfully.
This is also where a stable internet connection matters in practical terms. I would avoid starting an important request from a weak signal, especially if I am away from home or moving between networks. If the app seems slow, the safest response is not repeated tapping. Wait, check whether the action was recorded, and then continue. Repeated submissions are a poor habit in any financial workflow.
Recovery is easier when I keep my own notes. Before submitting a request or committing funds, I would record the amount and the expected timing in a private budget note. That does not replace the app’s records, but it gives me a reference if I need to reconstruct what I intended. Screenshots can also help me remember what I reviewed, provided they are stored securely and do not expose sensitive information to anyone else using the phone.
If I lose access to the phone, change devices, or need to reinstall the app, I would expect to follow the normal account-recovery process and would make sure my contact details remain current. I would not create a duplicate account simply because the first login is inconvenient. In financial services, rushing recovery can create more confusion than waiting and using the proper route.
The community model introduces another reliability consideration: the experience is not controlled only by the app interface. Borrower outcomes can depend on whether lenders respond, while lenders must accept that a social lending decision is not identical to placing money in a conventional savings product. I see this as the central limitation of the service. The app can organize the interaction, but it cannot remove the uncertainty that comes from involving other people.
Privacy and attention are part of the experience
Because this is a finance app, I would be selective about where and when I use it. A crowded café, a shared workplace, or a public transport seat is not the best place to review personal financial details. I would use a screen lock, avoid sharing account screenshots casually, and keep notifications from displaying more information than necessary on a locked screen.
I would also resist checking the lending side whenever I feel bored. Browsing opportunities can make money feel abstract, while the consequences remain real. A short written lending policy for myself—how much I can commit, what level of uncertainty I accept, and when I stop—makes the app easier to use responsibly.
Device constraints and who should choose another option
The app is available for users who meet the Everyone content rating, which makes it broadly approachable from an age-classification standpoint. That should not be confused with suitability for every financial situation. Someone who cannot reliably repay a short-term obligation, who is already juggling several urgent debts, or who needs a large long-duration loan should look beyond this kind of service.
SoLo Funds is also not a complete replacement for a bank account, a budgeting app, or a credit-building product. A bank may be better for everyday deposits and scheduled bills. A budgeting tool may be better for identifying why a shortfall keeps happening. A conventional lender may be more appropriate when the need is larger and repayment must be spread over a longer period, although that option brings its own costs and conditions.
On the device side, users should remember that the current version is 2.19.0. Keeping the app current is sensible for compatibility and maintenance, but I would not update moments before an urgent transaction without leaving time to reopen the app and check that everything works normally. If the phone is old, nearly full, or frequently loses connection, a desktop or established banking alternative may be less stressful for an important payment.
People who want a completely predictable financial product may also prefer a traditional route. The appeal here comes from flexibility and participation in a lending community. If that uncertainty makes you uncomfortable, the app’s distinctive feature becomes its main drawback rather than its main advantage.
My performance verdict after weighing the trade-offs
I see SoLo Funds: Lend & Borrow as a focused tool for short-term borrowing and community lending, not as a universal answer to financial pressure. Its strongest quality is the way it brings a specific money need into one dedicated workflow. The free entry point and clear two-sided purpose make it easy to understand: borrowers seek help on their own terms, and lenders decide whether participating suits them.
Its perceived speed is best when I prepare first and use a reliable connection, but I would never promise myself that an urgent request will be resolved immediately. Its resource demands should be reasonable for ordinary phones that meet the Android requirement, while the real demand is attention: reading carefully, tracking commitments, and resisting impulsive decisions. Reliability depends not only on the software but also on the people and circumstances involved.
My most important recommendation is to define the exit plan before starting. Borrowers should know exactly where repayment will come from. Lenders should know how much money they can leave committed without affecting essentials. Both sides should keep personal records, avoid repeated taps during a slow session, and treat every transaction as a real financial commitment rather than a casual in-app action.
For someone facing a small, temporary gap with a realistic repayment date, I think the app is worth considering. For someone dealing with an ongoing shortage, uncertain income, or a need for a conventional long-term loan, I would choose a different financial solution first. The app can organize a short-term decision, but it cannot make an unaffordable decision safe.
Overall, I would recommend it to careful users who understand the community-lending model and want an alternative to asking friends directly or relying immediately on a standard credit product. I would skip it if I needed guaranteed timing, predictable long-term financing, or a complete personal-finance dashboard. Used with a written budget and realistic expectations, it has a clear purpose; used impulsively, its convenience can become the very thing that makes a difficult month harder.
4.6
5.63K Reviews
Pros
- Borrowers can request small loans without traditional credit checks.
- The app encourages direct
- community-based lending between members.
- Loan requests and repayment details are presented in a simple interface.
- Users can build a borrowing history through consistent repayments.
- Mobile access makes managing requests and repayments convenient.
Cons
- Availability and features may vary depending on your location.
- Borrowing limits may be low for users who need larger amounts.
- Late repayments can affect your standing within the community.
- Lender returns are not guaranteed and may involve repayment risk.
- Some users may face verification or account approval delays.


